Replace your mortgage
Cash-out refinance
A new, larger mortgage replaces your current one. The difference pays off your other debts, so you are left with one loan and one payment.
Mortgage Loan Officer · Salt Lake City
I help self-employed borrowers, 1099 contractors, first-time buyers, investors and families rebuilding their credit get into a home, and help homeowners weigh whether their equity should pay off high-interest debt.
01Debt consolidation
If you own a home, its equity can pay off credit cards, car loans and other high-interest debt, leaving one loan to manage. I’ll show you whether it actually leaves you better off, and tell you plainly when it doesn’t.
Replace your mortgage
A new, larger mortgage replaces your current one. The difference pays off your other debts, so you are left with one loan and one payment.
Keep your mortgage
A line of credit against your equity, alongside the mortgage you have. Draw what you need, when you need it.
Keep your mortgage
A fixed amount borrowed as a second loan, paid back on a set schedule, while your current mortgage stays as it is.
Consolidating can stretch short-term debt over a longer term. Your home secures the loan. I lay out the trade-offs side by side before you decide anything.
02Why banks say no
Banks mostly lend by one rulebook. I can shop a wide range of programs, including loans built for people whose income or history looks different on paper.
What the bank said: “Your tax returns show too little income.”
Write-offs save you on taxes but make your income look small to a bank.
Qualify with 12 months of bank statements
What the bank said: “We need two years of W-2s.”
Contractors, drivers, creators and commission earners get bounced by W-2 rules.
1099 programs use what you actually earn
What the bank said: “Your score is too low.”
Medical bills, a rough year or a thin file can drag a score down fast.
Flexible-credit programs, or a plan to raise it
What the bank said: “Your debt-to-income is too high.”
A car payment and a few cards can eat the room a lender wants for your house payment.
A pay-down order that frees up the most room
What the bank said: “It’s too soon since your bankruptcy.”
Bankruptcy, foreclosure or a short sale doesn’t have to mean waiting forever.
Some programs allow shorter waiting periods
What the bank said: “Your personal income doesn’t support it.”
Investors with several properties often hit a wall on personal income.
DSCR loans qualify on the property’s rent
03Not ready yet? Perfect.
If buying today isn’t the right move, I’ll tell you straight and map out exactly what to fix. No judgment, no pressure, and no charge to put the plan together.
We go over your income, debts, savings and credit together. A first conversation doesn’t require a credit pull.
Which card to pay first, what to leave open, how much to save, and the targets we’re aiming for.
We touch base as you hit milestones, so you’re never guessing whether it’s working.
When the numbers line up, we pick the right program and you go house hunting with confidence.
04Loan options
Every program has its own rules, costs and trade-offs. My job is to lay them side by side so you can pick the one that fits.
Cash-out refinance, HELOC or home equity loan.
Homeowners with high-interest debtQualify on deposits instead of tax returns.
Self-employed · business ownersQualify on a profit-and-loss statement.
Self-employedQualify on the 1099s you receive.
Contractors · commission prosQualify on the property’s rental income.
Real estate investorsUse savings or investments to qualify.
Retirees · high assetsFHA-insured, with a lower down payment and flexible credit guidelines.
First-time buyers · rebuildersPrograms that can cover part of your down payment.
Buyers short on cash05Reviews
“He gave me lots of loan quotes throughout the house hunting process and was fully transparent. I trust him like he’s family.”
“He will explore every single option, tell you pros and cons, and work with you to help you find the best solution for your needs.”
“He worked his butt off and helped me get into my first home while finding every opportunity to help get the best bang for my buck!”
06About Austin
I got into mortgages in 2020 the hard way. I was self-employed and buying my second house, and the financing was tough. I went through three different lenders and got denied twice. My income wasn’t that unique, it just didn’t fit the box. That’s when I decided I wanted to help people in the same situation.
Today I work with the people the big banks turn away. The business owner whose tax returns don’t show what they really make. The 1099 contractor. The investor going after the next property. The family rebuilding after a rough stretch on their credit.
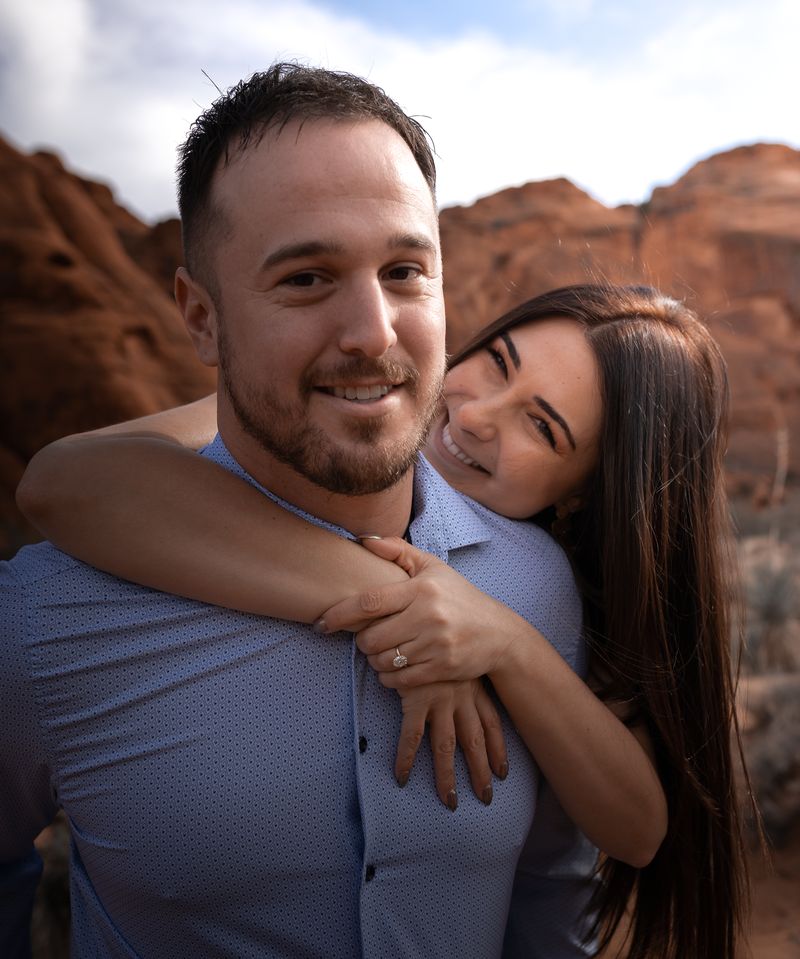
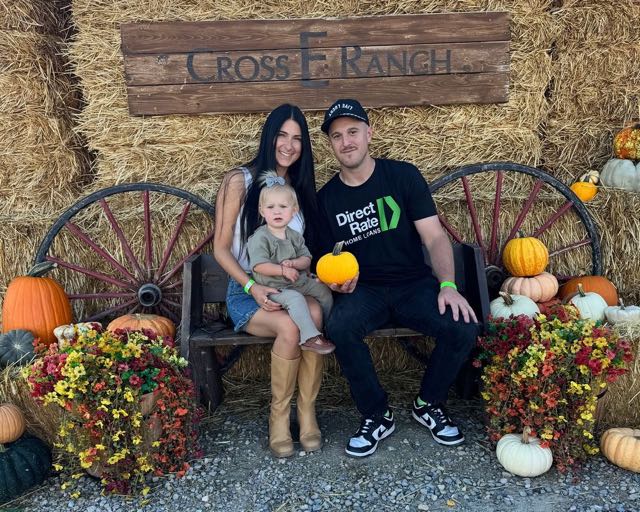
I married my wonderful wife in 2023. She works in real estate law, and in 2022 she was a big part of opening the mortgage company I work with today. Together we make an amazing team that understands the ins and outs of the real estate market. In 2025 we welcomed our first child, which really opened my eyes to the financial challenges working families face.
I was born and raised in Salt Lake, Utah. I love it here and never plan to leave. I grew up blue collar, so I understand a good work ethic, and I bring it to every file. My clients rate me 5.0 stars on Google. They say I’m transparent, I explain everything, and I’ll go the extra mile to get a deal to the closing table.
07Questions
No. We can have a full conversation first and build you a plan without doing a hard pull on your credit. All this work is done with a soft pull, which does not hurt your credit or show up as an inquiry, but gives us all the information we need to get you pre-approved.
Historically, yes. Recently, no. Non-QM programs used to be rare and carried higher risk, which led to higher rates. Now, non-QM programs have a proven track record of fewer delinquencies and foreclosures than in the past. Often they can carry the same interest rate as the traditional route for self-employed borrowers, and in some cases an even lower one.
I am not a credit repair company. But in my experience, most credit repair companies charge a monthly fee to improve your credit, so they're incentivized not to fix it quickly and to keep you on the hook for many months. I can give you similar advice and better results in less time than most credit repair companies, at no cost to you. I'm incentivized to fix your credit quickly, so you can get into a home faster.
Not at all. This is one of the most common situations I help with. Bank statement loans, P&L loans, 1099 programs, asset utilization loans, and more are built for you.
It depends on where you're starting. Oftentimes, if it's basic credit repair, I can get clients where they need to be in 1–2 months. If you have bankruptcies, multiple collections, or very unique income, it can take anywhere from 2 to 12 months.
Often, if you have equity in your home. A cash-out refinance, a HELOC or a home equity loan can pay off higher-interest debt. I’ll compare them with you, including the costs, before you decide.
Call, text or email me and tell me where you’re at. I’ll get back to you and we’ll find a time to go over your options.